
Your Pension Contribution Is Not a Deduction—It's Deferred Ownership
“Every payday, your pension contribution leaves your payslip—but it doesn't leave your ownership. It's not money lost; it's money set aside for your future. Discover why changing the way you think about your pension—from a deduction to deferred ownership—can help you stay engaged with your retirement savings, monitor your contributions, and build greater financial confidence for the future. This article explores how a simple mindset shift can lead to better retirement decisions.”
Your Contribution Is Not a Deduction — It Is Deferred Ownership
The money leaving your payslip is not lost; it is moved to your future self, and it still belongs to you.
Every payday, a line on your payslip shows money leaving for your pension, and it is easy to see that amount as something you have lost. It can feel like another deduction, similar to tax, reducing the amount you take home each month. Because of this perception, many pension members ignore their pension statements, never monitor their retirement savings, and rarely consider making additional voluntary contributions. However, what appears to be a deduction is actually something very different.
"The money leaving your payslip is not lost; it is moved to your future self, and it still belongs to you."
Moved, Not Lost
A pension contribution does not disappear. Instead, it moves from your present self to your future self while remaining your money. It is not transferred into your employer's account, nor does it become government revenue. Rather, it forms part of your personal retirement savings, held for your benefit and intended to support you when you retire. Seeing your pension as an asset you own rather than as a deduction changes the way you think about saving. Instead of viewing pension contributions as money you no longer have, you begin to see them as an investment in your future lifestyle and financial independence.
Your Mindset Shapes Your Behaviour
The way you think about your pension influences the decisions you make every month. Members who view their pension as money that has been taken away often contribute only the minimum required, avoid checking their statements, and see little value in increasing their retirement savings. By contrast, members who recognise that their pension belongs to them are more likely to review their statements regularly, keep their records accurate, monitor their growing balance, and consider additional Tier 3 contributions to strengthen their retirement position. Although the monthly contribution may be identical, the long-term outcome can be very different because of the behaviour that follows the mindset.
In Ghana, Under Act 766
For workers in the formal sector, Ghana's pension system requires an overall contribution of 18.5% of basic salary. Of this amount, the employee contributes 5.5%, while the employer contributes 13% on the employee's behalf. This means that for every cedi deducted from your salary, your employer contributes more than twice that amount toward your retirement savings. Part of these contributions builds your funded Tier 2 pension, which is managed by a licensed trustee such as Standard Pensions Trust and safeguarded by an independent custodian.
The Same Deduction, Two Different Futures
Imagine two colleagues, Ama and Kojo, who earn exactly the same salary. Every month, the same 5.5% employee contribution is deducted from each of their payslips. Kojo thinks of it simply as "the deduction." He never opens his pension statement, rarely thinks about his retirement savings, and plans to access the money as soon as he becomes eligible. Ama, however, thinks differently. She refers to it as "my pension." She reviews her pension statement regularly, watches her retirement balance grow, and even decides to add a small monthly Tier 3 contribution to strengthen her future retirement income. Although the amount leaving both payslips is exactly the same, their attitudes lead them down very different financial paths. One person ignores an asset they already own, while the other actively manages and grows it.
Key Takeaway
What You Should Do Next
- Open your latest pension statement and view the "deduction" for what it truly is—your own growing retirement balance.
- Compare the pension contribution shown on your payslip with your pension statement to confirm that your employer has remitted your contributions correctly and that they have been recorded accurately.
- If you notice any discrepancies, raise the matter with your employer or Human Resources department first. If additional support is required, contact Standard Pensions Trust (SPT) for assistance.
- Consider strengthening your retirement savings by setting up a small voluntary Tier 3 contribution that fits comfortably within your monthly budget.
This article is intended solely for general pension education under the Retirement Edge Program. It does not constitute personalised financial, investment, tax, or legal advice. Access to pension benefits is governed by scheme rules and the regulations of the National Pensions Regulatory Authority (NPRA). Contribution rates and regulatory requirements may change over time; members should confirm current information before making financial decisions.
Respond to this article with emojis
0 reactions so far
Related Posts
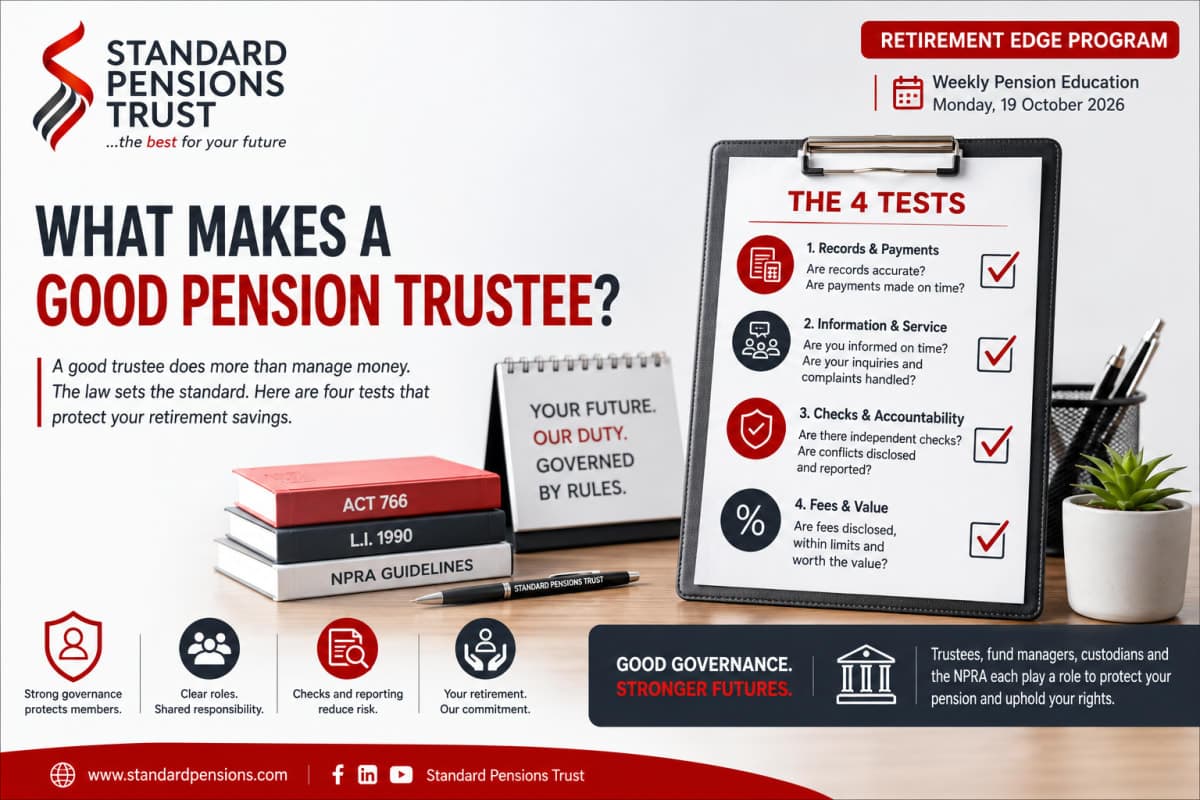
What Makes a Good Pension Trustee? 4 Regulatory Tests Beyond Fees
Fees are easy to compare, but they cannot tell you whether your pension records are accurate or your complaints addressed. Discover the four core legal tests under Ghana’s Act 766 and NPRA guidelines to properly evaluate your pension trustee
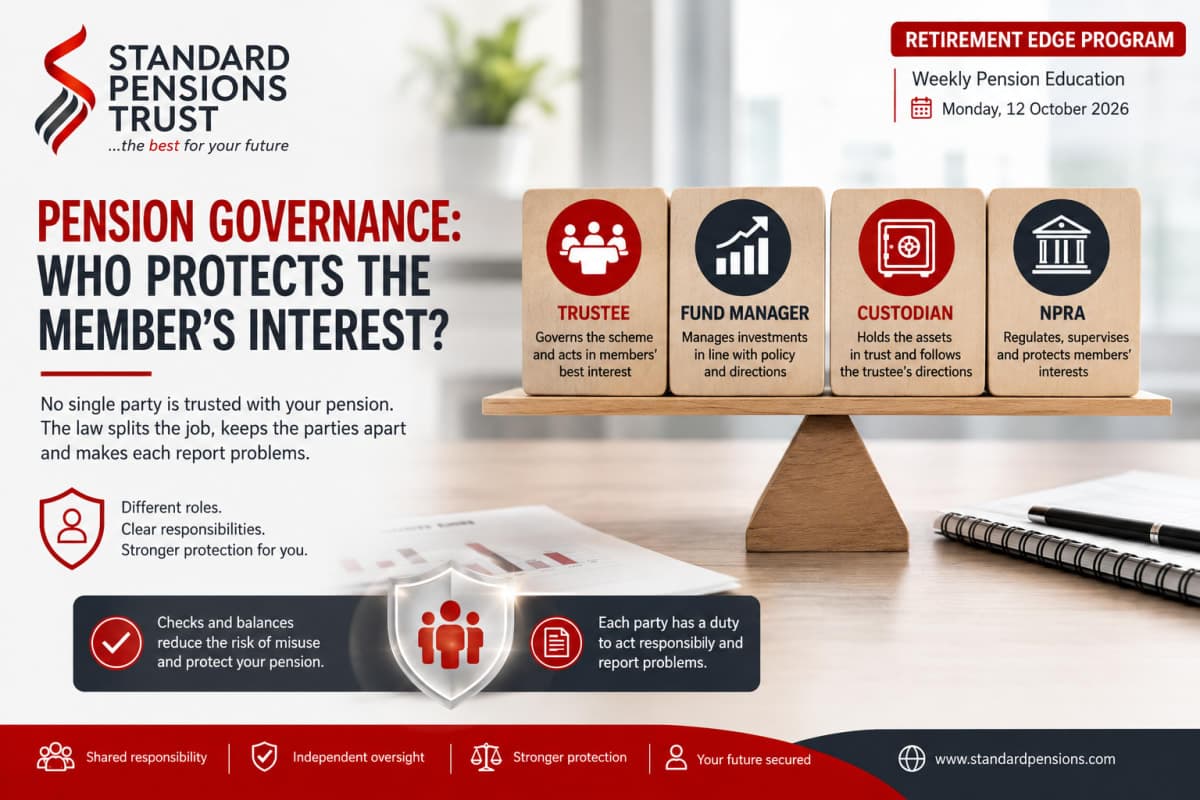
Pension Governance: Who Protects the Member’s Interest?
Who is responsible for protecting your pension? Discover how trustees, fund managers, custodians and the NPRA work together to support accountability and protect pension members in Ghana. This week’s Retirement Edge explains the roles behind pension governance and what you can do to stay informed about your retirement savings.
Why Every Workplace Needs Pension Education
Pension documents may arrive on a legal clock, but understanding them requires more than delivery. Discover why timely pension education helps employees understand contributions, statements, porting, and their retirement benefits.


Subscribe to our Newsletter
Get pension updates, retirement planning tips, and trusted insights delivered to your inbox.