
Why Small Contributions Still Matter: The Secret to Building a Stronger Retirement
“Many people believe they need to earn more before they can start saving for retirement. In reality, one of the biggest advantages in pension planning is consistency—not contribution size. Discover how small, regular pension contributions through Tier 2 and Tier 3 can grow into meaningful retirement savings over time, and why building the habit of saving today can make all the difference tomorrow.”
Why Small Contributions Still Matter
In a pension, the amount you can keep up matters more than the amount you wish you could afford.
Many workers believe they need a large amount of money before they can begin saving for retirement.
"My contribution is too small to make a difference. I'll save properly when I earn more."
This is one of the most common—and costly—misconceptions in retirement planning. Waiting for the "perfect" time often means losing valuable years of consistent saving and investment growth.
Small Contributions Are More Powerful Than You Think
A strong pension is rarely built through a few large deposits. Instead, it grows from small, regular contributions made consistently over many years.
For example, saving just GH¢5 per day—about the cost of a snack—adds up to roughly GH¢150 each month or GH¢1,800 each year. Over ten years, that becomes approximately GH¢18,000 in contributions before any investment growth.
Because pension contributions are invested over your working life, your retirement savings have the opportunity to grow beyond the amount you personally contributed.
Consistency Beats Occasional Large Payments
- Efua saves GH¢150 every month automatically.
- Yaw waits until he has extra money and contributes GH¢2,000 once in three years.
After three years, Efua has contributed approximately GH¢5,400—more than twice Yaw's contribution—and has also developed a lifelong savings habit.
Regular monthly contributions not only build larger retirement savings but also create financial discipline that lasts throughout your career.
Automatic Saving Makes Success Easier
The easiest way to remain consistent is to automate your savings.
If your contribution leaves your account automatically before you spend your income elsewhere, you eliminate the temptation to postpone saving.
For workers in Ghana's formal sector, Tier 2 contributions are already deducted automatically through payroll. Tier 3 allows you to create the same habit voluntarily, even if you work in the informal sector or earn an irregular income.
The Real Asset Is the Habit
Your first retirement contribution does not need to be large.
Choose an amount you know you can maintain—even during difficult financial months.
As your income increases, you can always increase your contributions. The important thing is to build the habit today rather than waiting for tomorrow.
Key Takeaway
What You Should Do Next
- Start a small monthly Tier 3 contribution today.
- Choose an amount you can comfortably maintain every month.
- Automate your contributions so saving becomes effortless.
- Review your pension statement regularly to confirm your contributions are being received.
- Increase your monthly contribution whenever your income grows.
Respond to this article with emojis
0 reactions so far
Related Posts
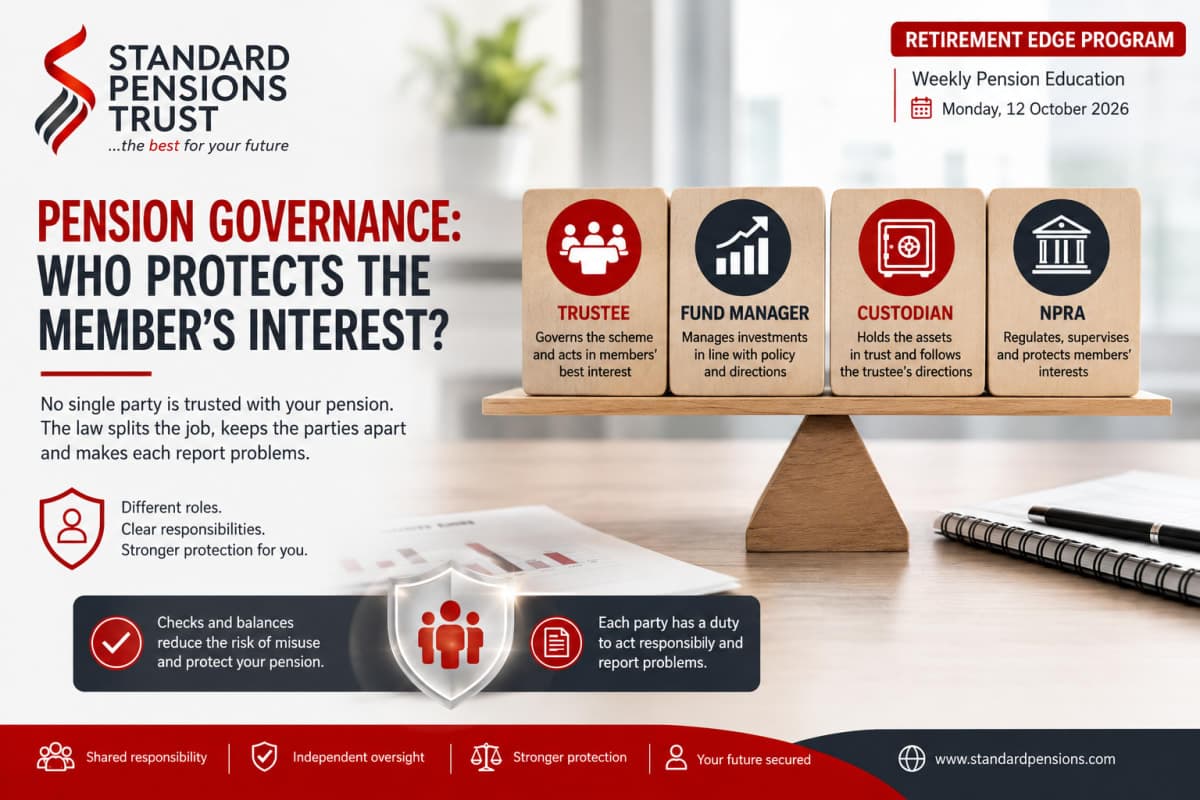
Pension Governance: Who Protects the Member’s Interest?
Who is responsible for protecting your pension? Discover how trustees, fund managers, custodians and the NPRA work together to support accountability and protect pension members in Ghana. This week’s Retirement Edge explains the roles behind pension governance and what you can do to stay informed about your retirement savings.
Why Every Workplace Needs Pension Education
Pension documents may arrive on a legal clock, but understanding them requires more than delivery. Discover why timely pension education helps employees understand contributions, statements, porting, and their retirement benefits.
The Employer’s Role in Building Retirement Security
An employer’s pension responsibility goes beyond deducting contributions. Learn how timely remittance, accurate contribution reporting, and proper member records help turn payroll deductions into secure retirement benefits.


Subscribe to our Newsletter
Get pension updates, retirement planning tips, and trusted insights delivered to your inbox.