
Why Every Workplace Needs Pension Education
“Pension documents may arrive on a legal clock, but understanding them requires more than delivery. Discover why timely pension education helps employees understand contributions, statements, porting, and their retirement benefits.”
Why Every Workplace Needs Pension Education
Every workplace with a pension scheme has the same gap: members' documents arrive on a legal clock, but almost nothing requires anyone at work to explain them. Fill that gap when a document arrives.
What the Rules Deliver, and What They Leave Out
A new member of a workplace scheme must be given an information document and a membership certificate within sixty days of joining.
Within three months of the end of each financial period, normally a calendar year, comes a benefit statement listing any period with no contribution paid (L.I. 1990, Regulations 37 to 39 and 59).
Each month the employer must also give members a pay-record showing the deduction, the employer's contribution and the date the contributions were paid to the trustee (Regulation 108).
Who explains them? Sensitising the public is the regulator's job (Act 766, Section 7(i)), and a trustee must, as far as reasonably practicable, answer members' questions and handle their complaints (Regulation 40).
The NPRA's 2024 governance guidelines add an education and sensitisation committee on every scheme board (paragraph 41).
Beyond that, nothing we read in the Act, the Regulations or the guidelines makes anyone at work explain these papers, save telling provident-fund joiners about vesting rules (Benefit Administration Guidelines, paragraph 5).
What Members Take to the Regulator
The NPRA received 512 complaints in 2025, few beside 2.1 million active contributors to the basic national scheme.
Porting — moving benefits between schemes, for example after a job change — accounted for 55 per cent; defaulting employers 17 per cent; and contributions 10 per cent (NPRA 2025 Annual Report).
Complaints are not proof of misunderstanding, and a session cannot make an employer pay.
It can, however, explain the choices and clocks around porting and contributions, and where to go when an employer defaults.
Why Timing Matters
A review of 76 randomised experiments in 32 countries found that financial education improves knowledge and behaviour on average, with a smaller effect on behaviour measured six months or more later (Kaiser and colleagues, 2022).
An earlier review found that even large programmes had negligible effects on behaviour twenty months on, and recommended “just-in-time” education tied to a decision (Fernandes and colleagues, 2014).
Who Belongs in the Room?
Payroll holds the pay-records and must reply in writing within fourteen days to a worker's question about contributions (Regulation 110).
The trustee must respond to members' inquiries (Regulation 40).
Unions and staff associations can carry questions to both, and the Act gives organised labour two seats on the NPRA's Board (Section 8).
Occupational schemes must also arrange for members to nominate at least a third of the trustees, or of a corporate trustee's directors, subject to exceptions (Sections 141 and 142).
Whoever runs a session, us included, should keep product selling out of it or label it. Being invited in is itself useful to any trustee.
NPRA 2025 Annual Report, year ended 31 December 2025, and L.I. 1990. The complaint figures show what members complained about, not why.
Your documents are owed on a legal clock. Understanding them is on no clock at all, so put a date on it: the weeks after statements are handed out.
What You Should Do Next
In Ghana, Under Act 766 — The Pinpoints
Information: Act 766 s7(i); L.I. 1990 reg 40.
Documents: regs 37 and 38 (sixty days; the employer passes them on within 14 and 7 working days); reg 39(1)(a), (3)(b) and (6) (the employer passes the statement on within 14 working days); reg 59; reg 108 (seven working days after payment); reg 110; reg 119.
Voice and representation: s8(1)(g) to (i), which also seat the Ghana Employers' Association and the National Pensioners Association; ss141 and 142 and reg 6, with exceptions at s141(6) and s142(9).
Remittance: s3(3); s3(7), deducted money held in trust until paid.
Scope of “no duty to explain”: the whole Act, all 156 regulations and seven NPRA guidelines read by OCR (Gazette Nos. 211/2024 and 13/2025).
Education committee: governance guidelines para 41(5)(c).
Vesting: benefit guidelines para 5(4)(e).
Regulations: made text, in force 28 March 2011.
Respond to this article with emojis
0 reactions so far
Related Posts
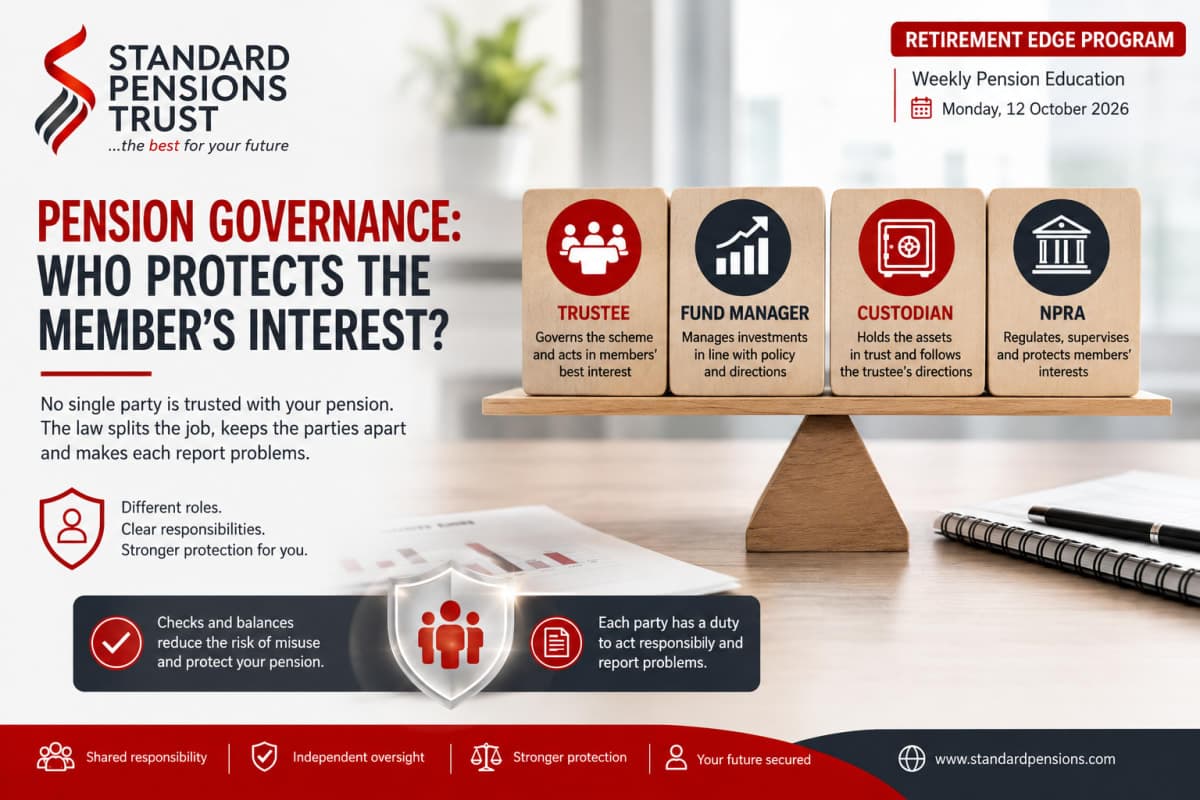
Pension Governance: Who Protects the Member’s Interest?
Who is responsible for protecting your pension? Discover how trustees, fund managers, custodians and the NPRA work together to support accountability and protect pension members in Ghana. This week’s Retirement Edge explains the roles behind pension governance and what you can do to stay informed about your retirement savings.
The Employer’s Role in Building Retirement Security
An employer’s pension responsibility goes beyond deducting contributions. Learn how timely remittance, accurate contribution reporting, and proper member records help turn payroll deductions into secure retirement benefits.
Why Pension Funds Think Long-Term
Learn why pension funds invest for the long term, how Ghana’s pension investment rules work, and what trustees, fund managers and custodians must do to protect members.


Subscribe to our Newsletter
Get pension updates, retirement planning tips, and trusted insights delivered to your inbox.