
Tier 2 Explained: Your Mandatory Occupational Pension
“Every month, 5% of your basic salary is set aside for your Tier 2 pension, but do you know where that money goes and how it grows? Learn how Ghana's mandatory occupational pension scheme works, who manages it, and the simple steps you can take today to protect your retirement savings.”
Tier 2 Explained: Your Mandatory Occupational Pension
What your monthly 5% really is, where it goes, and the one thing to check today
Each month, 5% of your basic salary leaves your payslip for your Tier 2 pension. Many workers see that line and quietly wonder: where does it go, and is it really mine? If you have asked the same question, this article is for you.
What Tier 2 actually is
Tier 2 is the second part of Ghana’s three-tier pension system. It is a mandatory occupational pension: “occupational” means it comes through your job, and “mandatory” means the law requires it for every formal-sector worker. Unlike Tier 1, which SSNIT manages and which pays you a monthly pension, Tier 2 is managed by a licensed private trustee such as Standard Pensions Trust. Your contributions sit in a personal account in your name. It is a defined-contribution scheme, which simply means what you receive depends on how much goes in and how those savings grow.
Where your 5% goes — and how it grows
Under the National Pensions Act, 2008 (Act 766), you and your employer together contribute 18.5% of your basic salary each month. SSNIT keeps 13.5% for Tier 1. The remaining 5% is your Tier 2 contribution, sent to your trustee. Your money is not left idle: a licensed pension fund manager invests it within rules set by the National Pensions Regulatory Authority (NPRA), and an independent custodian holds the assets for safekeeping. Each monthly 5%, plus the investment returns earned, is added to your account. Over a career, these steady contributions compound into a meaningful lump sum. That is why Tier 2 is deferred retirement value, not extra salary — the deduction is money saved for your future, not money lost
A simple example
Kwame earns a basic salary of GH¢4,000. His Tier 2 contribution is 5% — GH¢200 a month, or GH¢2,400 a year. Left to accumulate and grow over decades, that monthly GH¢200 becomes a retirement lump sum worth far more than the same cash would have meant if spent today
Common misconceptions to clear up
Three beliefs cause the most confusion. First, that Tier 2 is the same as SSNIT — it is not; it is separate, and held in your name by your trustee. Second, that you can withdraw it at any time — in general, Tier 2 is paid as a lump sum at retirement, from age 60, or from 55 if you retire early. Third, that statements do not matter — in fact, your statement is how you confirm that your money is arriving and growing.
What You Should Do Next
- Check your latest Tier 2 statement so you know your current balance.
- Confirm your name, date of birth, SSNIT number, and employer details are correct.
- Ask your employer or HR whether your 5% is being remitted on time each month.
- Keep your pension documents safely.
- Contact Standard Pensions Trust or visit www.standardpensions.com if anything is unclear.
Enjoyed this article?
Join our WhatsApp Channel for pension tips, updates and new articles.
Respond to this article with emojis
0 reactions so far
Related Posts
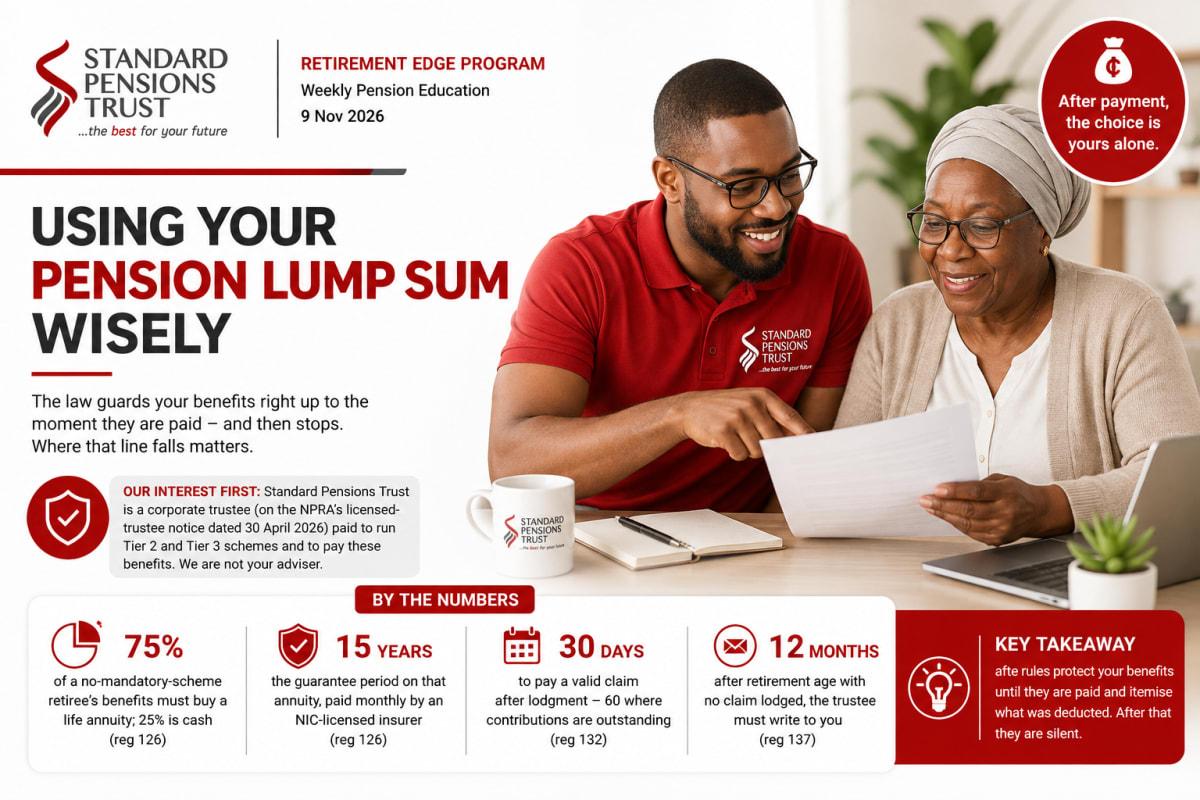
Using Your Pension Lump Sum Wisely: What to Know Before You Spend
Your pension lump sum represents years of contributions and savings. But what happens to the legal protection once the money is paid? Understand how Tier 2 and Tier 3 benefits are paid, what deductions to check, and the important steps to take before using your retirement money.
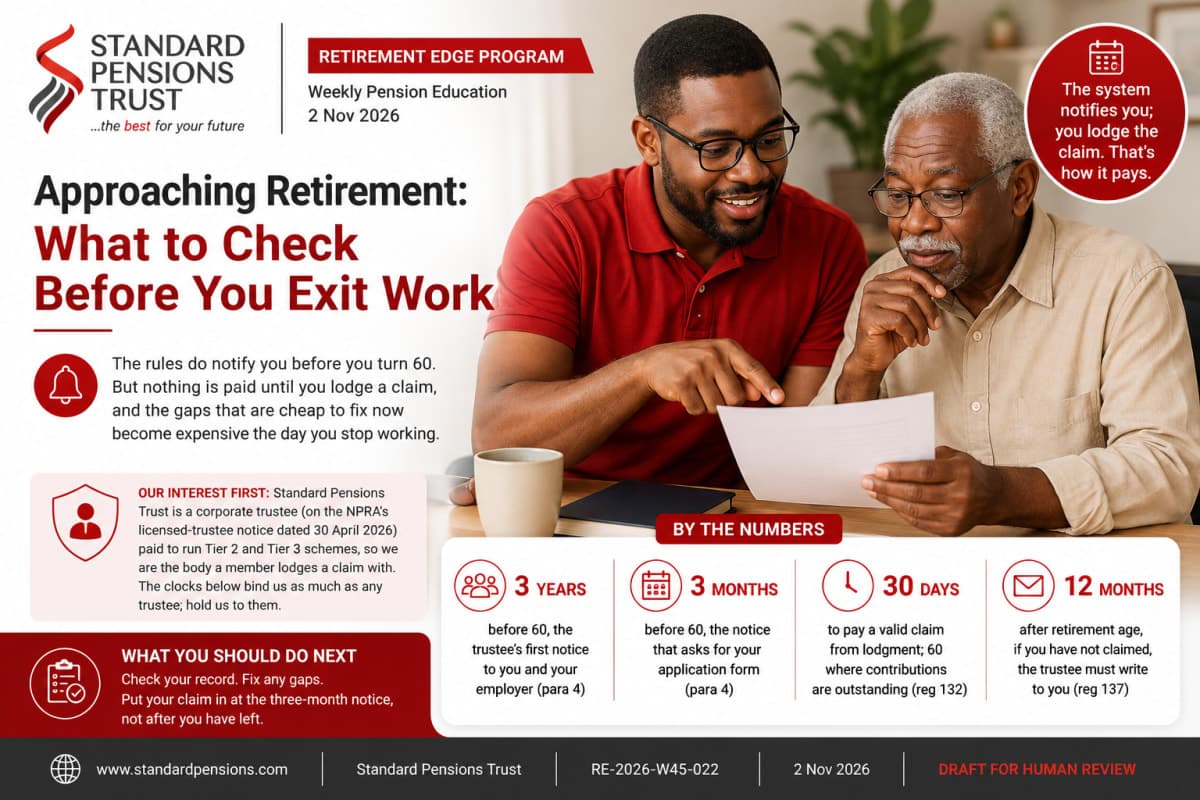
Approaching Retirement in Ghana: What to Check Before You Exit Work
Learn what to check before retirement in Ghana. Understand Tier 2 pension notices, contribution records, claim requirements, payment timelines and steps to secure your retirement benefits.
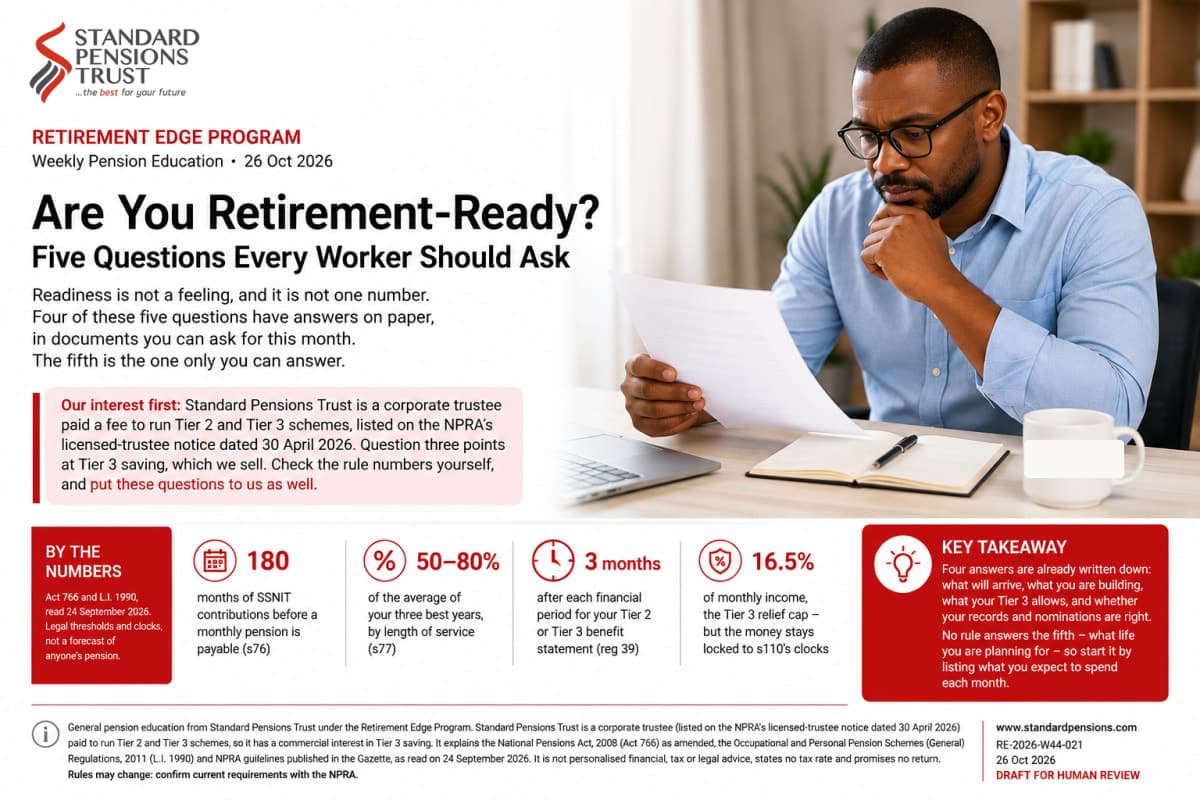
Are You Retirement-Ready? Five Questions Every Worker Should Ask
Readiness is not a feeling, and it is not one number. Explore five questions every worker should ask about SSNIT pension eligibility, Tier 2 benefits, Tier 3 savings, benefit statements, records and nominations—and start planning for the life you want in retirement.


Subscribe to our Newsletter
Get pension updates, retirement planning tips, and trusted insights delivered to your inbox.