
What Makes a Good Pension Trustee? 4 Regulatory Tests Beyond Fees
“Fees are easy to compare, but they cannot tell you whether your pension records are accurate or your complaints addressed. Discover the four core legal tests under Ghana’s Act 766 and NPRA guidelines to properly evaluate your pension trustee”
Retirement Edge · Pension Governance
What Makes a Good Pension Trustee?
Fees are the easiest thing to compare, and they compound for decades, so compare them carefully. But a fee cannot tell you whether your records are right or your complaints answered. The rules set the standard for those; here are four tests, and how to apply them.
TEST 01Are the records and payments right?
A trustee keeps the scheme's accounts and a separate account for each member, valued at market value at least monthly (L.I. 1990, regulations 57 and 58).
It must pay a valid claim within thirty days where no contributions are outstanding, or within sixty days where they are (regulation 132). It must also notify members three years, and again three months, before they reach 60 (NPRA Benefit Administration Guidelines, paragraph 4).
The NPRA licenses a company only once satisfied it can administer schemes (regulation 2). These requirements make record accuracy, sound administration and timely payment important things to verify.
TEST 02Does it tell you on time, and listen?
New members must receive an information document covering fees and a named contact, and a certificate naming the trustee, within sixty days (regulations 37 and 38). Statements must follow within three months after each financial period (regulation 39).
The trustee must, as far as reasonably practicable, answer inquiries and deal with complaints (regulation 40).
The NPRA's 2024 governance guidelines also require an education and sensitisation committee on every scheme board, and an annual general meeting where members may question the scheme's affairs (Corporate Governance Guidelines, paragraphs 39 and 41(5)(c)).
We cannot say how widely both happen: ask your scheme. Check whether documents arrive when expected, whether questions receive answers, and whether members have a meaningful opportunity to raise concerns.
TEST 03Are the checks built in?
A corporate trustee needs an independent director (Act 766, section 123) and an approved compliance officer who reports directly to the NPRA and may not be dismissed for true and fair non-compliance reports (regulation 2; Compliance Officers Guidelines, paragraphs 3, 4 and 6).
The NPRA judges directors and key staff on competence, honesty and integrity, independence of mind and financial soundness (Fit and Proper Guidelines, paragraphs 5 and 6), though members cannot see that assessment.
Conflicts must be disclosed and recorded in a book members may inspect on request (regulation 44). Significant events must be reported to the NPRA within three working days (regulation 45).
When assessing a trustee, ask how independent oversight works, how compliance concerns reach the regulator, and how conflicts are recorded and handled.
TEST 04Are its fees disclosed, limited and worth it?
Fees must be disclosed to anyone applying to join (regulation 17) and may not exceed limits the NPRA sets (sections 145 and 163). Nothing may be deducted unless prescribed or authorised (section 162).
The governance guidelines ask scheme boards to oversee service providers' fees with the value received in mind (paragraph 34).
Neither a lower nor a higher fee tells you whether the other three tests are met, so check all four. None of them promises a return.
By the Numbers
NPRA notice and 2025 Annual Report; L.I. 1990. These are two snapshots from different dates. The report names none of the 22 trustees. These are legal clocks and sector figures, not a rating of any trustee.
Compare fees, then check the floors: records and payments right, information on time, checks built in, and fees disclosed and within limits. Every test applies to us too.
What You Should Do Next
For Members
Check your own documents against the clocks in regulations 37 to 39
and keep the dates. Ask to inspect the conflicts record book
(regulation 44), and attend your scheme's annual general meeting
or ask how to put a question in writing.
If your employer chose the scheme (regulation 156; section 129),
members still nominate at least a third of the trustees or of a
corporate trustee's directors, subject to exceptions (sections
141 and 142). If a test fails, use the complaint route below and
tell your employer.
For Employers
Choosing or reviewing a master trust? Ask each trustee in writing for its fees (regulation 17), its record against the payment and statement clocks, and how its compliance officer reports. Check the NPRA's lists at npra.gov.gh under Trustees, and check their dates. A lapsed list proves nothing.
For Tier 3 Savers
A personal pension scheme is your choice, and your employer must provide the payroll services to join it (section 115). Before choosing, check the NPRA's lists, ask for the fee disclosure you are owed as an applicant (regulation 17), and ask in writing how members raise questions.
If a Trustee Falls Short
Write to the trustee first (regulation 40). The NPRA receives and investigates complaints of impropriety (section 7), and a member or beneficiary may ask the NPRA Board in writing to review a trustee's decision (section 202).
In Ghana, Under Act 766 — The Pinpoints
Licensing: Section 123(2)(c); section 125(1)(a); L.I. 1990, regulation 2(1), (4) and (5).
Records and payments: Section 121(g) and (h); regulation 57(1); regulation 58(1) and (3); regulation 132(1) and (2).
Information: Regulation 37(2); regulation 38(2); regulation 39(1)(a); regulation 40 (as far as reasonably practicable); regulation 44(3); regulation 45(1)(a), whose three-working-day clock the governance guidelines repeat for listed events (paragraph 62).
Fees: Section 145; section 162; section 163; regulation 17(4)(c).
Scheme choice: Section 115(a); section 129; regulation 156 (participation agreement); member nomination under sections 141 and 142, with exceptions at section 141(6) and section 142(9).
Redress: Section 7(j); section 202.
NPRA guidelines: Read by OCR from the Gazette scans on the NPRA website. Corporate Governance (Gazette No. 211, 19 November 2024), paragraphs 34(1)(j), 39, 41(5)(c) and 62; Compliance Officers (same Gazette), paragraphs 3(1), 4(3) and 6(1); Fit and Proper, NPRA/GD/FAP/01/24, and Benefit Administration, NPRA/GD/BAP/01/24 (both Gazette No. 13, 21 January 2025), paragraphs 5, 6(1) and 4(1).
List dates: Lists read 15 September 2026: licensed-trustee notice v17 (29 names); good-standing list v48 (22 names, valid until 31 July 2026; no later list found). Standard Pensions Trust appears on both.
Respond to this article with emojis
0 reactions so far
Related Posts
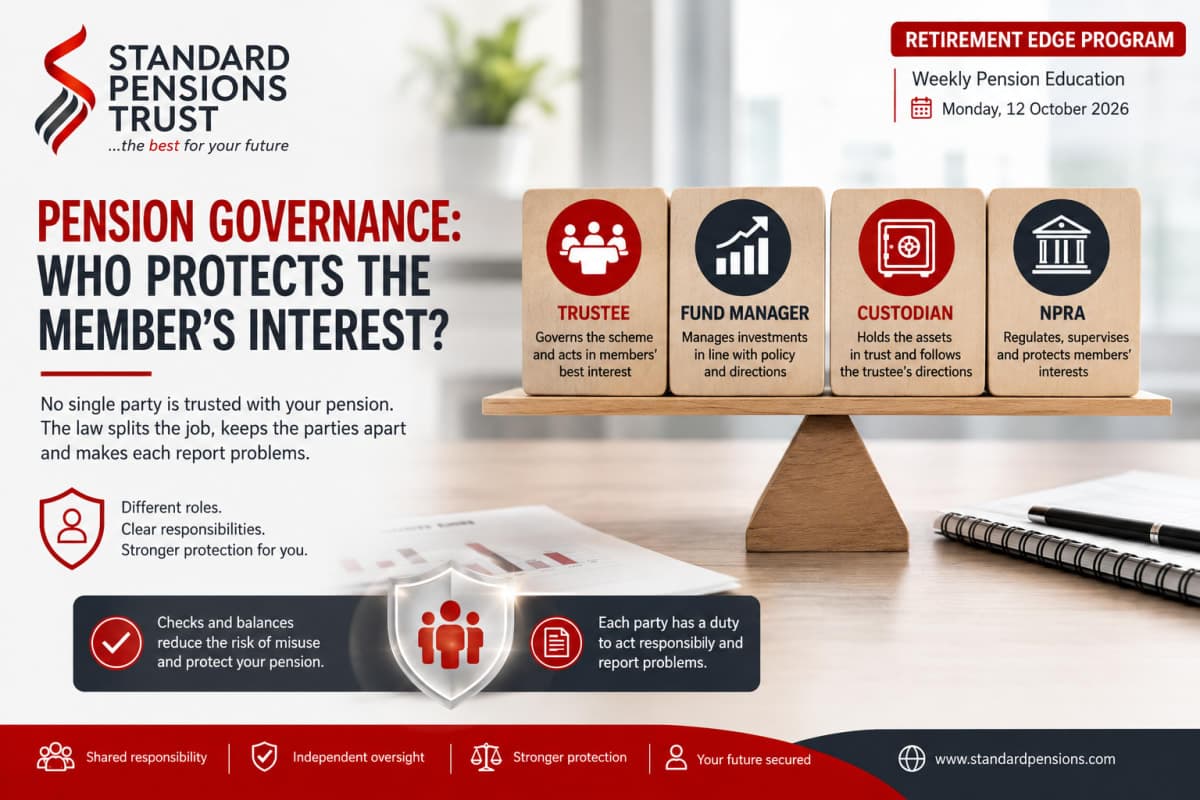
Pension Governance: Who Protects the Member’s Interest?
Who is responsible for protecting your pension? Discover how trustees, fund managers, custodians and the NPRA work together to support accountability and protect pension members in Ghana. This week’s Retirement Edge explains the roles behind pension governance and what you can do to stay informed about your retirement savings.
Why Every Workplace Needs Pension Education
Pension documents may arrive on a legal clock, but understanding them requires more than delivery. Discover why timely pension education helps employees understand contributions, statements, porting, and their retirement benefits.
The Employer’s Role in Building Retirement Security
An employer’s pension responsibility goes beyond deducting contributions. Learn how timely remittance, accurate contribution reporting, and proper member records help turn payroll deductions into secure retirement benefits.


Subscribe to our Newsletter
Get pension updates, retirement planning tips, and trusted insights delivered to your inbox.