
The Power of Starting Early: Why Time Is Your Greatest Pension Asset
“Discover why starting your pension early is the smartest financial decision. Learn how compound growth and time can build a stronger retirement future.”
The Power of Starting Early: Time Is Your Strongest Pension Asset
Why the cheapest pension you will ever build is the one you start today.
Many young workers believe retirement is something to worry about later. They often say,
"I will take my pension seriously later—I am still young, and money is tight."
It sounds reasonable. After all, nothing seems to happen if you postpone saving for a few years. However, when it comes to pensions, every year of delay carries a hidden cost. The biggest advantage in retirement planning is not earning more money—it is giving your money more time to grow.
How Compound Growth Works
Your Tier 2 and Tier 3 pension contributions do not simply sit in an account. They are invested with the goal of generating long-term returns.
Compound growth means your investment earns returns, and those returns are reinvested to generate additional returns. Over many years, this creates a snowball effect where growth begins slowly but accelerates over time.
It contributes no money of its own, yet over an entire career it can add more to your retirement savings than your own contributions.
Why Starting Early Matters
The true fuel of compounding is time—not necessarily the amount you save.
Someone who starts saving early can contribute relatively small amounts consistently and still build significant retirement wealth. Conversely, someone who starts much later has fewer years for investments to grow and often needs to contribute much larger amounts each month to reach similar retirement goals.
In Ghana, mandatory Tier 2 pension contributions begin from your very first salary under the National Pensions Act, 2008 (Act 766). These funds are managed by licensed trustees such as Standard Pensions Trust under NPRA regulations.
Tier 3, however, is voluntary. That means the decision about when to begin rests entirely with you.
Ama and Kofi: A Tale of Two Savers
Consider the following illustration using monthly savings of GH¢200 and an assumed annual investment growth rate of 10%. These figures are purely illustrative and should not be interpreted as guaranteed investment returns.
| Ama | Kofi | |
|---|---|---|
| Starting Age | 25 | 45 |
| Monthly Savings | GH¢200 | GH¢200 |
| Total Contributions | GH¢84,000 | GH¢36,000 |
| Retirement Value | ≈ GH¢759,000 | ≈ GH¢83,000 |
Ama contributes just over twice as much as Kofi throughout her working life, yet she retires with approximately nine times more money.
For Kofi to achieve the same retirement outcome within his remaining fifteen years, he would need to save approximately GH¢1,800 every month instead of GH¢200.
Key Takeaway
Every year you postpone retirement saving makes your desired retirement significantly more expensive. The cheapest pension you will ever build is the one you start today.
What You Should Do Next
- Start saving today—even if your initial contribution is small.
- If you currently only contribute to Tier 2, consider beginning a Tier 3 pension this month.
- Regularly check your pension statements to ensure contributions are being received on time.
- If you are in your 20s or 30s, take advantage of your greatest retirement asset—time.
- If you are over 40, don't be discouraged. The second-best time to begin is today.
Respond to this article with emojis
0 reactions so far
Related Posts
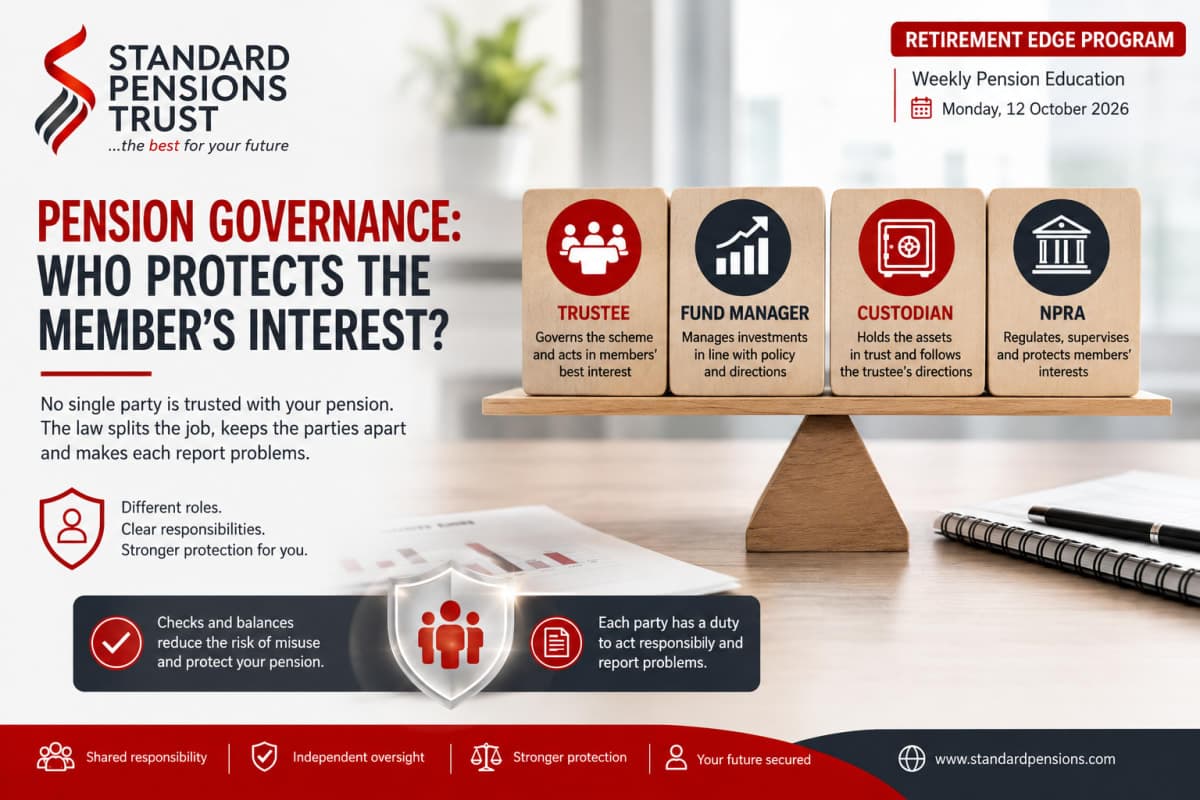
Pension Governance: Who Protects the Member’s Interest?
Who is responsible for protecting your pension? Discover how trustees, fund managers, custodians and the NPRA work together to support accountability and protect pension members in Ghana. This week’s Retirement Edge explains the roles behind pension governance and what you can do to stay informed about your retirement savings.
Why Every Workplace Needs Pension Education
Pension documents may arrive on a legal clock, but understanding them requires more than delivery. Discover why timely pension education helps employees understand contributions, statements, porting, and their retirement benefits.
The Employer’s Role in Building Retirement Security
An employer’s pension responsibility goes beyond deducting contributions. Learn how timely remittance, accurate contribution reporting, and proper member records help turn payroll deductions into secure retirement benefits.


Subscribe to our Newsletter
Get pension updates, retirement planning tips, and trusted insights delivered to your inbox.